Smoke Damage Insurance Claims in California: What Bulletin 2025-7 Means for Homeowners
By Buena Park Fire & Water Damage Pros 6 min read
Quick answer
Bulletin 2025-7, issued by the California Department of Insurance on March 7, 2025, tells insurers that smoke damage can be covered under policies insuring against direct physical loss, and that smoke claims must be fully and fairly investigated. It does not guarantee payment: coverage still depends on your policy and the facts.
What Bulletin 2025-7 actually says
The bulletin is addressed to property and casualty insurers handling smoke damage claims for homes and businesses in or near California wildfire areas. It came out after the January 2025 Los Angeles fires, when thousands of owners whose houses were still standing filed smoke claims and some were told smoke was not covered.
- Recent court cases did not remove smoke coverage. The Department reads the California Supreme Court's 2024 Another Planet decision as confirming that smoke damage can be covered when a policy insures against direct physical loss, and treats a 2025 appeals decision that went against homeowners as limited to its own facts.
- Each claim turns on its own facts. Coverage depends on the specific policy language and the evidence in that claim.
- Investigation is required. Evidence of smoke damage must be fully and fairly investigated, and denying a smoke claim without an appropriate investigation is not reasonable.
- Testing costs belong with the insurer. Insurers should not make policyholders spend substantial money to investigate their own claim. When professional testing is warranted, the Department expects the insurer to arrange and pay for it.
- It applies broadly. The expectation covers all insurers, including the California FAIR Plan.
The bulletin also encourages insurers to consider sending low-cost at-home test kits as a first step on some claims, with more investigation if the results call for it.
What the bulletin does not do
Read accurately, Bulletin 2025-7 is guidance on how claims must be handled. It is not a rule that every smoke claim gets paid, and it does not set cleaning or testing standards of its own. An insurer can still deny a claim after a proper investigation if the policy or the evidence supports that.
The law is still moving. In September 2026 the governor signed smoke damage bills, including AB 1642 and AB 1795, that take effect January 1, 2027 and call for state testing and cleanup standards over the following years. They are not retroactive, and details are still being written, so confirm what applies to your claim date.
Why this matters in Buena Park and north Orange County
Buena Park has no wildland edge, but Santa Ana winds carry smoke and ash across north Orange County from canyon and hillside fires. Residents saw it during Canyon Fire 2 in 2017, the Blue Ridge and Silverado fires in 2020 and the Airport Fire in 2024. Ash on patios and a smell in the closets can mean residue inside the attic and ducts too.
Smoke also travels inside the city. A kitchen fire in one unit of a two-story apartment block, or in the attached garage of a 1960s ranch home, sends smoke through shared attics and returns. The duty to investigate thoroughly and fairly that the bulletin cites comes from the Insurance Code and claims regulations that apply to claims generally.
Homes closer to the hills see more of the wildfire version. Our page on fire and smoke damage restoration in La Habra covers that city's hillside exposure and its Los Angeles County Fire Department coverage.
How to document smoke damage for your claim
Smoke damage is easy to dispute because much of it is faint or hidden. Build a record of where residue is and when it appeared.
- Date-stamped photos and video of every room, including ceilings, vent covers, window tracks and the inside of closets and cabinets.
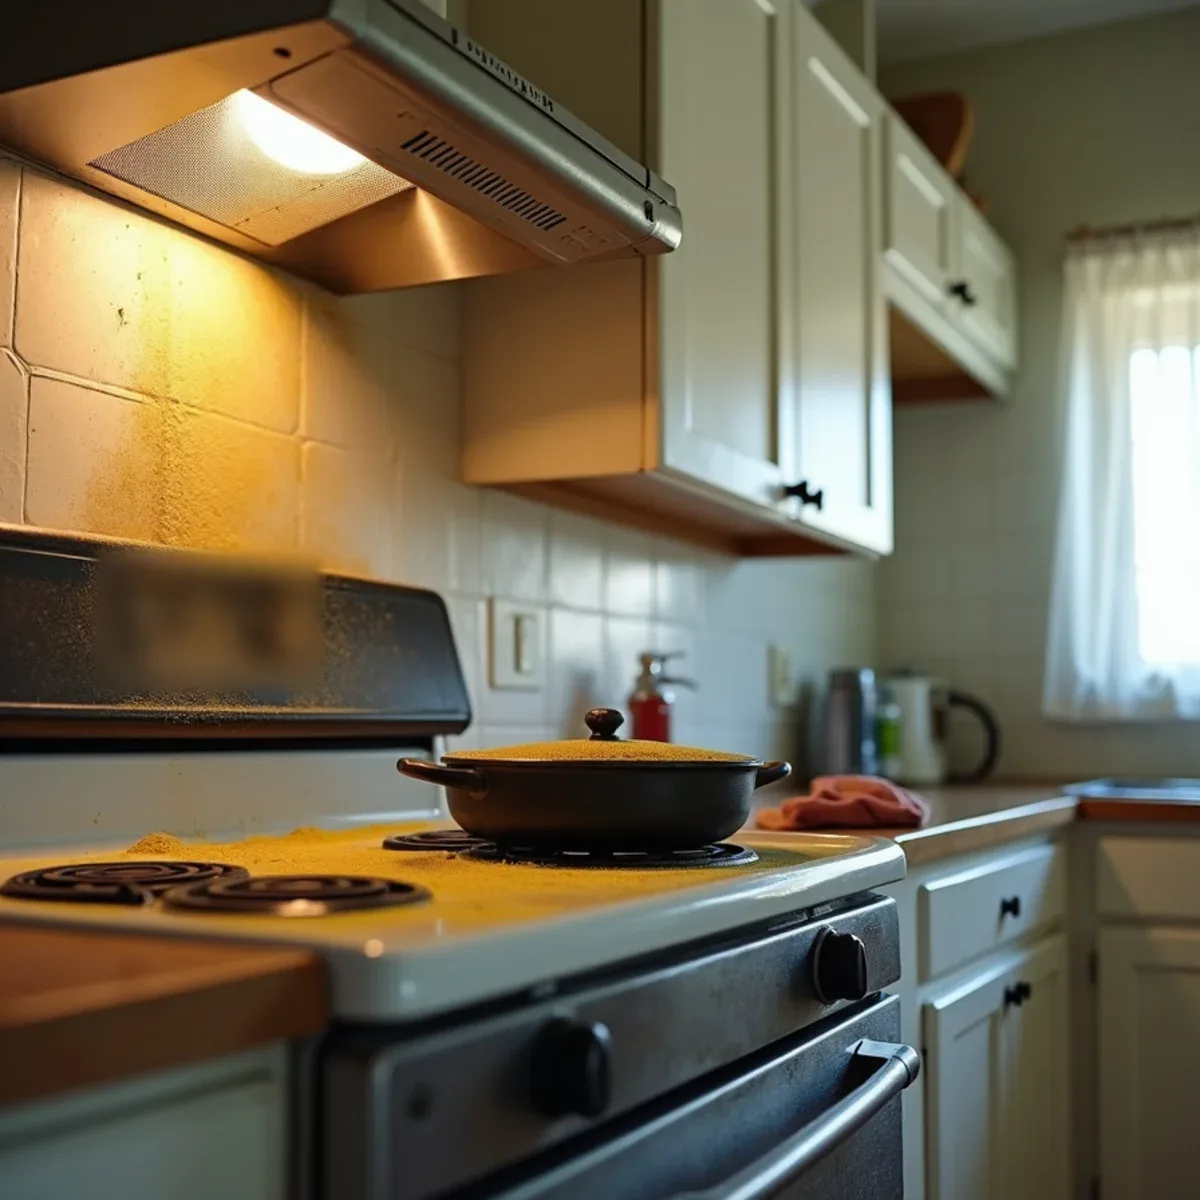
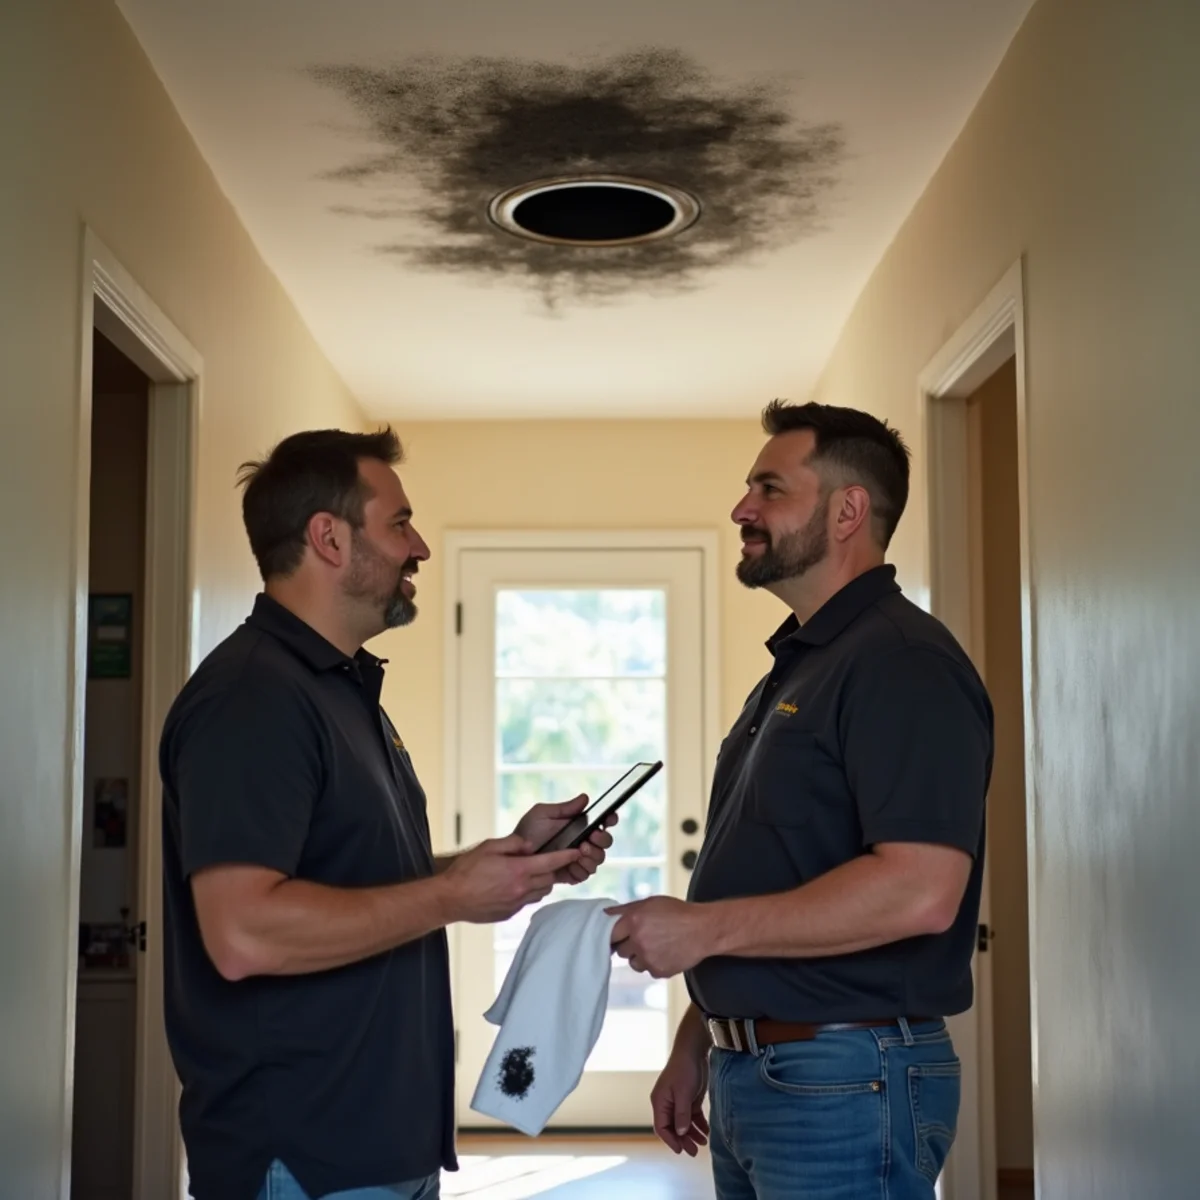
- Close-ups of residue: wipe a clean white cloth across a surface and photograph the result next to the spot.
- The HVAC filter, photographed and kept in a sealed bag.
- A simple odor log: which rooms smell, how strongly, and whether it gets worse when the house warms up.
- Outside evidence: ash on the roof, patio and cars, with the date and any OCFA or news report of the fire that caused it.
- Receipts for anything you have paid for since the loss.
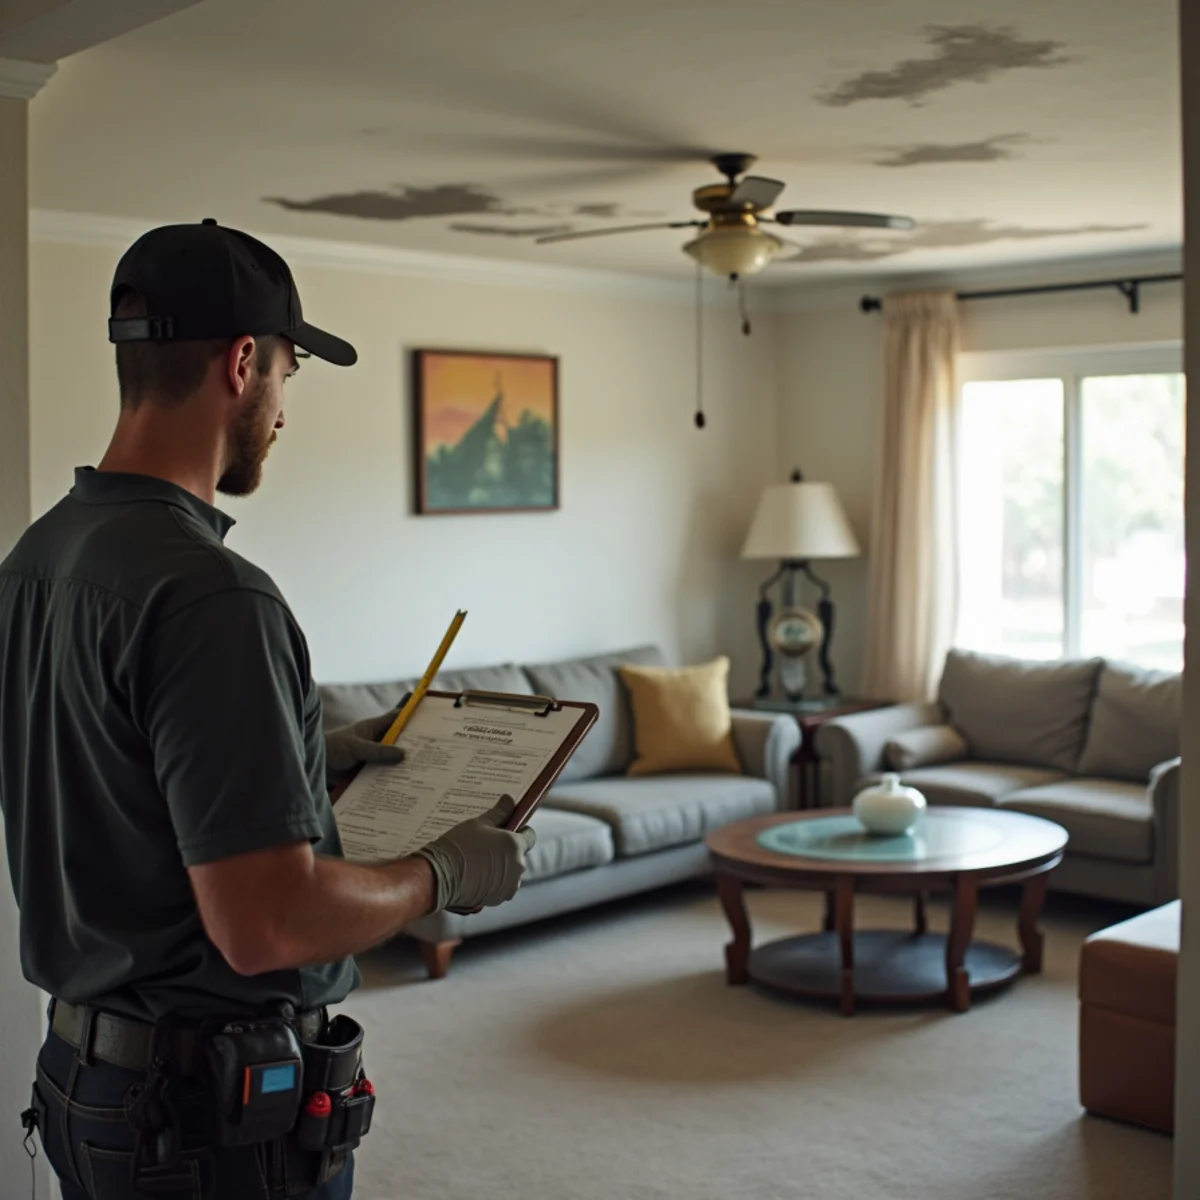
A professional assessment adds weight. A smoke damage cleanup crew can document residue in the attic, ducts and wall cavities with photos and an itemized scope your adjuster can review, and can meet the adjuster on site.
Building a contents inventory
Your insurer will ask for a list of damaged belongings. Start it early and work room by room, because memory fades quickly once rooms are packed up.
| Column | What to write |
|---|---|
| Room and item | Kitchen: stand mixer, white |
| Brand, model, age | Brand name, model number if visible, bought about 2021 |
| Condition | Soot film, odor, melted, or cleanable |
| Proof | Photo number, receipt, bank statement or online order |
| Decision | Clean, replace, or waiting on adjuster |
Do not throw anything away without a photo and, for anything of value, your adjuster's okay. A contents cleaning and pack-out crew inventories and photographs items as they box them, which gives you a list for the claim and a record of what was cleaned versus discarded.
From the job site: what makes a smoke claim hold up
Restoration crews see the same smoke claims succeed or stall for the same reasons. The difference is rarely the policy language; it is the record built in the first days.
- The HVAC filter was saved. A filter pulled after the smoke event, bagged and photographed, is some of the clearest evidence of how much residue moved through the house.
- Photos came before cleaning. Wipe marks on a white surface, gray film on window tracks and residue in the attic near the vents, all dated, carry more weight than a description written later.
- Testing matched the question. Low-cost at-home kits can start a conversation, but when coverage turns on residue in the ducts or insulation, sampling by a qualified professional answers it, and the bulletin expects insurers to pay when that testing is warranted.
- The scope separated the losses. Smoke cleaning, odor treatment, duct work, contents and any repairs on their own lines make it easier for an adjuster to approve what is clearly documented.
- Nothing was thrown out early. Smoke-damaged fabrics and furniture kept until the adjuster saw them, or until written approval, avoided arguments about what was lost.
Cleaning to prevent further damage should not wait for the adjuster. Just document first, keep samples of anything removed when you can, and note the date on everything.
Living expenses, public adjusters and who speaks for you
Additional living expenses
If smoke makes the house unlivable, most homeowners and renters policies include additional living expenses, also called loss of use or Coverage D. It usually pays the increase over your normal costs: a rental or hotel, extra meals out, a longer commute. Keep every receipt and ask your adjuster in writing how long coverage runs and what is needed to extend it.
Public adjusters and attorneys
In California, only a licensed public adjuster or an attorney may negotiate a claim on your behalf. Public adjusters are licensed by the Department of Insurance and usually charge a percentage of the settlement, so get the fee in writing and check the license on the Department's website. A restoration contractor can document damage and explain its scope, but it cannot negotiate your claim. You choose the contractor; your insurer cannot require you to use theirs.
For help with the cleanup side, call (831) 303-1192 at any hour. Buena Park Fire & Water Damage Pros connects Buena Park and Orange County homeowners with independent fire and smoke restoration contractors. Every fire restoration crew we send is licensed where California requires it, and insured, and you get the scope and price in writing before work starts.
The bottom line on smoke damage claims
For Orange County homeowners, the practical takeaway is to document smoke damage thoroughly and ask for an inspection. The bulletin says denying a smoke claim without an appropriate investigation is not reasonable, and that insurers should pay for professional testing when it is warranted. If a claim stalls, United Policyholders, a California nonprofit, publishes free claim guides and help for disaster survivors, and the Department of Insurance takes consumer complaints.
For the house itself, call (831) 303-1192 at any hour. Crews provide photo documentation, an itemized scope for smoke damage cleanup and contents cleaning and pack-out, and can meet your adjuster on site. Negotiating the claim stays with you, or with a licensed public adjuster or attorney.
Related questions
Does homeowners insurance cover smoke damage if my house did not burn?
It can. Bulletin 2025-7 says smoke damage can be covered where a policy insures against direct physical loss, but each claim depends on the policy wording and the evidence. Document residue and odor carefully and ask for an inspection.
Can my insurer deny a smoke claim without inspecting the house?
The Department of Insurance says it is not reasonable to deny a smoke damage claim without an appropriate investigation. If that happens, ask the insurer in writing for an inspection and the basis for the decision, and contact the Department if you still have concerns.
Who pays for smoke damage testing?
Under the bulletin, insurers should not make you incur substantial costs to investigate your own claim, and when professional testing is warranted the Department expects the insurer to arrange and pay for it. Some insurers may start with at-home test kits.
Do I need a public adjuster for a smoke claim?
Not always. Many claims settle with good documentation and a clear scope. On large or disputed claims a licensed public adjuster may help, for a fee; read the contract before signing.